Market Intelligence
Grit Real Estate’s KSh20.5 Billion Kenya Portfolio: Debt Restructuring, Asset Disposals and Institutional Acquisition Opportunities
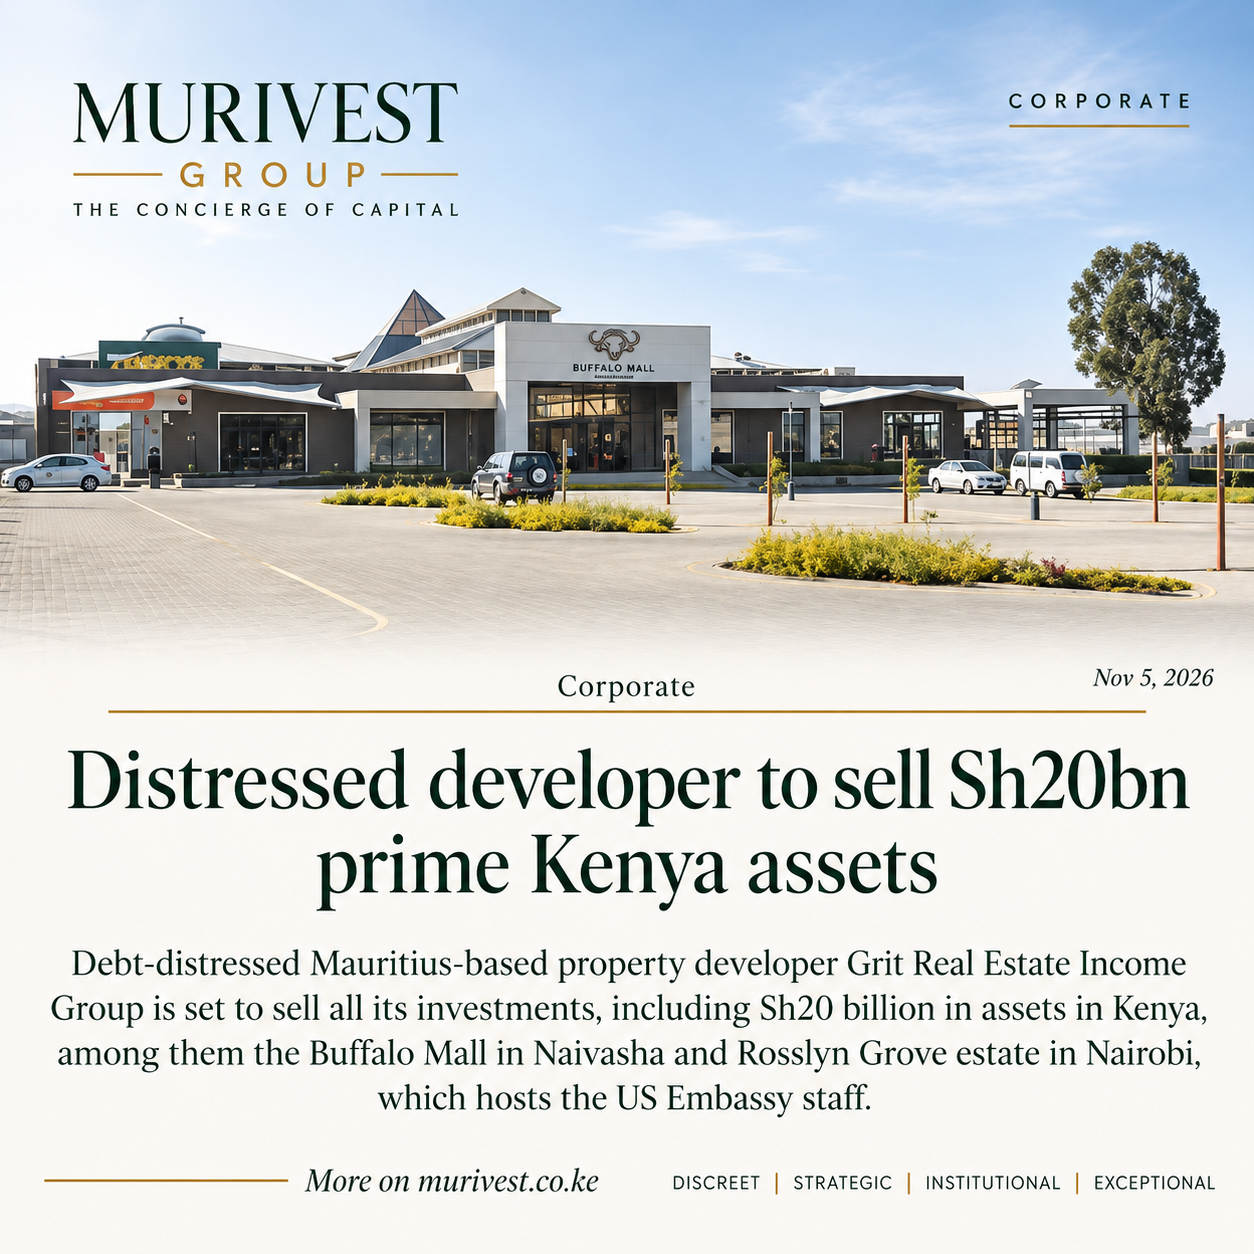
MURIVEST GROUP LTD / MARKET INTELLIGENCE / KENYA
Grit Real Estate’s KSh20.5 Billion Kenya Portfolio: Debt Restructuring, Asset Disposals and Institutional Acquisition Opportunities
commercial real estate assets in Nairobi representing Kenya's commercial property investment market"
/>
The proposed disposal of Grit Real Estate Income Group's African property portfolio marks an important development in the Kenyan commercial property market. With approximately KSh20.5 billion in Kenyan income-producing assets last valued in June 2025, the transaction could bring several established commercial properties into a new ownership cycle.
Executive Summary
Grit Real Estate Income Group, a Mauritius-based pan-African property investment company, is pursuing a broad disposal programme covering its real estate holdings and development interests. The process follows mounting financial pressure, elevated financing costs, delayed financial reporting and a suspension of trading in its ordinary shares.
The Kenyan portfolio was valued at approximately US$158.2 million, equivalent to KSh20.5 billion, as at June 2025. This represented approximately 16 per cent of the group's reported US$989 million global property portfolio at that date.
Its Kenyan exposure includes Rosslyn Grove, Buffalo Mall, Eneo at Tatu City, Orbit Africa and Imperial Distribution Centre. These properties span diplomatic accommodation, retail, commercial offices and logistics.
The disposal programme is not simply a property sale. It is also a corporate restructuring exercise involving secured lenders, subsidiary interests, existing financing arrangements and potential regulatory approvals.
For institutional buyers, the central question is not whether the assets are prominent. It is whether their contractual income, ownership interests, financing obligations and acquisition prices support an acceptable risk-adjusted return.
1. The Transaction: Understanding Grit's Disposal Strategy
Grit's proposed exit reflects a wider effort to simplify its corporate structure, reduce financial exposure and realise value from its remaining property interests.
In its announcement of 26 October 2026, the company confirmed that its board had accepted a conditional binding offer concerning its interests in Gateway Real Estate Africa (GREA) and Africa Property Development Managers Limited (APDM), together with certain associated assets and liabilities.
The proposed separation of these businesses forms one component of a wider restructuring process. The company has also been seeking offers for a substantial portion of its remaining income-producing property portfolio.
Grit reported that the preferred proposal for the wider portfolio had secured conditional support from senior secured creditors. Those creditors also indicated their willingness to continue providing working capital, subject to agreed conditions, while the transaction progresses.
These developments indicate creditor involvement in the disposal process. They do not, however, establish that every asset has been transferred or that all transactions have reached financial close.
The company has also indicated that it will engage regulators and shareholders regarding the future of its publicly listed status.
Institutional interpretation: Buyers should distinguish between an accepted offer, an executed sale agreement, satisfaction of conditions precedent and legal completion. Each represents a different stage of transaction certainty.
2. Kenya's KSh20.5 Billion Property Exposure
Kenya represents a material component of Grit's investment portfolio. Its properties occupy several commercially relevant locations and serve different categories of occupiers.
Grit's published portfolio information identifies five Kenyan assets. Their investment characteristics should be considered separately rather than treated as one homogeneous property portfolio.
2.1 Rosslyn Grove — Diplomatic Accommodation
Rosslyn Grove is a residential accommodation estate in Nairobi's Rosslyn area. The property serves the diplomatic accommodation market and has been associated with housing for United States Embassy personnel.
Its investment proposition differs from that of conventional residential developments. The relevant assessment includes the contractual lease structure, tenant obligations, currency denomination, remaining lease term, maintenance commitments and ownership interests.
A buyer should establish whether rental income is supported by enforceable contractual arrangements and whether any existing security interests affect the proposed transfer.
2.2 Buffalo Mall — Naivasha Retail
Buffalo Mall is a commercial retail centre serving Naivasha and its surrounding catchment.
Retail property performance depends on more than the physical quality of the building. Occupancy, tenant concentration, rental collection, service charge recovery, anchor tenant performance and local consumer demand all influence its income profile.
The acquisition analysis should examine the tenant schedule, lease expiry profile, outstanding rent, operating expenditure and any capital works required to maintain the property's competitive position.
2.3 Eneo at Tatu City — Commercial Offices and BPO
Eneo at Tatu City represents exposure to the commercial office and business process outsourcing sectors.
Its location within Tatu City's special economic zone provides a distinct commercial context. The building's income profile should be assessed against the strength of its anchor occupier, contractual rental commitments, building specification and future leasing requirements.
Institutional buyers should also examine the implications of the property's special economic zone status, applicable approvals and any conditions attached to its existing operations.
2.4 Orbit Africa — Industrial and Logistics
Orbit Africa adds an industrial and logistics component to Grit's Kenyan exposure.
Industrial property investment requires a different underwriting approach from retail or residential accommodation. Relevant considerations include building configuration, loading capacity, warehouse specifications, power infrastructure, tenant requirements and the availability of competing logistics facilities.
The property's income sustainability should be considered alongside its physical adaptability for future occupiers.
2.5 Imperial Distribution Centre — Pharmaceutical Logistics
Imperial Distribution Centre is a logistics and distribution property associated with pharmaceutical operations along the Mombasa Road corridor.
Its specialist use introduces additional diligence requirements. Buyers should examine the building's operational specifications, tenant obligations, environmental compliance, power infrastructure and suitability for alternative occupiers.
A specialist facility may offer a differentiated income proposition, but its re-letting potential should not be assumed without technical and occupational evidence.
3. Portfolio Composition and Investment Characteristics
The five properties demonstrate the diversity of Grit's Kenyan exposure. Their respective investment risks are linked to different occupier markets, contractual structures and operating requirements.
| Property | Location | Asset class | Principal diligence focus |
|---|---|---|---|
| Rosslyn Grove | Nairobi | Diplomatic accommodation | Lease and ownership structure |
| Buffalo Mall | Naivasha | Retail | Occupancy and rental collection |
| Eneo at Tatu City | Tatu City | Office and BPO | Anchor tenant and lease commitments |
| Orbit Africa | Nairobi region | Industrial and logistics | Occupier demand and technical condition |
| Imperial Distribution Centre | Mombasa Road | Distribution and logistics | Specialist use and tenant covenant |
The table describes asset categories and diligence considerations. It is not a valuation schedule or a statement of individual sale prices.
The approximately KSh20.5 billion valuation applies to the reported Kenyan income-producing portfolio as a whole. It should not be interpreted as a confirmed asking price or a current independent market valuation for each property.
4. The Financial Pressures Behind the Disposal
Real estate investment is capital intensive. Property owners commonly use secured borrowing to acquire, develop and operate assets. This can improve equity returns when rental income exceeds financing costs.
The same structure can become difficult to sustain when borrowing costs increase, valuations decline or refinancing becomes less accessible.
Grit has faced pressure from its financing arrangements and the wider interest-rate environment. Its publicly disclosed debt exposure has been reported at approximately US$500 million, equivalent to about KSh64.9 billion using the reported conversion.
The company has also experienced delays in publishing audited financial statements for the 18-month period ended 31 December 2025. Its ordinary shares were suspended from trading on the London and Mauritius exchanges in May 2026.
These developments have increased the importance of creditor coordination and transaction execution. Where assets secure existing borrowing, a purchaser must understand how the relevant security will be released or otherwise dealt with at completion.
4.1 Why Financing Costs Matter
Consider a hypothetical commercial property generating KSh100 million in annual net operating income.
If the property is financed using KSh1 billion of debt at an annual interest rate of 10 per cent, the annual interest obligation would be KSh100 million before principal repayments, tax and other financing costs.
The property's entire net operating income would therefore be absorbed by interest alone.
If the borrowing rate increased to 12 per cent, annual interest would rise to KSh120 million. The property would then experience a negative cash position before considering other obligations.
This simplified illustration shows why debt maturity, borrowing costs and rental income must be examined together. It does not describe Grit's actual financing on any individual Kenyan asset.
5. The Institutional Acquisition Opportunity
The proposed disposals may create an opportunity for institutional investors seeking established income-producing properties in Kenya.
Unlike speculative development, the acquisition of an operational property can provide access to an existing building, established occupiers and a documented rental history.
However, operational status alone does not establish investment quality. Buyers must determine whether the income is sustainable, whether the asset is appropriately priced and whether the transaction can be completed without unresolved legal or financial exposure.
5.1 Potential Buyer Categories
- Institutional property investors: Buyers seeking established commercial assets with a long-term ownership horizon.
- Private investment offices: Family offices and high-net-worth investors seeking direct exposure to income-producing real estate.
- Regional property operators: Businesses with the operational capacity to manage retail, office and logistics assets.
- Private equity and special situations capital: Investors capable of evaluating complex ownership structures, financing obligations and restructuring risks.
- Real estate investment partnerships: Qualified investors considering joint acquisitions with experienced operating partners.
These are potential buyer categories, not confirmed bidders or participants in Grit's disposal process.
6. The Murivest Institutional Acquisition Framework
Murivest applies a structured acquisition assessment to commercial property opportunities. The framework below identifies six areas that should be addressed before capital is committed.
Gate 1: Ownership and Legal Verification
Establish the registered proprietor, beneficial ownership, title position, subsidiary interests, encumbrances, security arrangements and restrictions affecting the proposed transfer.
Gate 2: Financial and Rental Verification
Review historical rent collection, contracted income, arrears, operating costs, tenant concentration, service charge accounts and outstanding liabilities.
Gate 3: Independent Valuation
Obtain a current independent valuation. Compare the proposed purchase consideration against market transactions, replacement cost, capital expenditure requirements and sustainable income.
Gate 4: Financing and Security
Determine existing lender exposure, repayment requirements, security releases, refinancing options and the availability of clear completion arrangements.
Gate 5: Physical and Operational Due Diligence
Commission appropriate structural, mechanical, electrical, environmental and property condition assessments. Review planning status, permits, insurance and operational compliance.
Gate 6: Exit and Income Sustainability
Model rental performance, vacancy scenarios, refinancing sensitivity, capital expenditure and the potential buyer universe at exit.
This framework is a Murivest-developed analytical approach. It is not an externally validated scoring model or a guarantee of investment performance.
7. Distressed Sales Are Not Necessarily Discounted Sales
One of the most important distinctions in distressed real estate transactions is the difference between seller financial pressure and the actual market value of the property.
A company facing liquidity constraints may have an incentive to dispose of assets quickly. However, the existence of debt distress does not automatically mean that a buyer will acquire the underlying property below market value.
The sale process may involve secured creditors, competing offers, existing leases and restrictions arising from financing agreements.
A transaction may also require the separation of property-owning entities from development or management businesses.
Buyers should therefore distinguish between:
- Acquisition of the underlying real estate.
- Acquisition of shares in a property-owning company.
- Acquisition of a development or management subsidiary.
- Acquisition of assets subject to existing security.
- Acquisition through a lender-supported restructuring.
These structures carry different tax, legal, operational and liability implications. Independent legal and tax advice is essential before selecting an acquisition route.
8. Implications for Kenya's Commercial Property Market
The proposed disposal has implications beyond the ownership of five individual properties. It highlights the relationship between international capital, local lending institutions and the financing of commercial real estate in East Africa.
First, the process may introduce new ownership into established commercial property markets. This could change asset management priorities, leasing strategies and future capital expenditure.
Second, the transaction demonstrates the importance of currency and interest-rate exposure in property investment. Assets may generate stable rental income while their owners face financing pressure at the corporate level.
Third, it reinforces the importance of transaction transparency. Institutional purchasers require reliable information on beneficial ownership, leases, debt, valuation and completion conditions.
Finally, the proposed sales may attract interest from domestic and international capital seeking established commercial assets. Whether this results in new investment, refinancing or a change of ownership will depend on the terms ultimately agreed.
9. Questions Institutional Buyers Should Ask
- Who holds legal and beneficial ownership of each property?
- What is the current independent market valuation of each asset?
- Which lenders hold registered charges or other security interests?
- What approvals and security releases are required for completion?
- Are rental receipts consistent with the reported contracted income?
- What is the remaining lease term for each principal occupier?
- What capital expenditure is required over the next five years?
- Are there unresolved tax, litigation or regulatory matters?
- Is the transaction structured as an asset purchase or a share purchase?
- What is the expected net return after financing, tax, operating costs and acquisition expenses?
10. Murivest's Market Perspective
The proposed Grit disposals provide a useful case study in the relationship between institutional property ownership, secured financing and asset liquidity.
For Kenya, the significance lies in the potential transition of established commercial assets into new ownership structures. Properties with functioning operations and established occupiers may attract interest from buyers seeking exposure to income-producing real estate.
However, the acquisition decision should remain asset-specific. A diplomatic housing estate, a regional shopping centre and a pharmaceutical distribution facility cannot be assessed using the same rental assumptions, operating model or exit strategy.
Murivest considers ownership verification, sustainable rental income, financing structure and independent valuation essential components of institutional acquisition analysis.
The opportunity, if one emerges, will be determined by the relationship between verified income, acquisition price and transaction risk rather than the headline value of the portfolio.
Conclusion
Grit Real Estate's proposed portfolio disposals represent a significant development in Kenya's commercial real estate landscape.
The approximately KSh20.5 billion Kenyan portfolio includes properties across diplomatic accommodation, retail, offices and logistics. Their potential transfer presents questions for property owners, lenders, institutional purchasers and regional investment managers.
The eventual outcome will depend on creditor arrangements, transaction documentation, regulatory requirements and the ability to complete the proposed disposals.
For prospective purchasers, disciplined underwriting remains essential. Financial distress at the corporate level does not remove the need for property-level due diligence.
The next phase of the process may help establish how international real estate capital is repositioned within Kenya's commercial property market.
Frequently Asked Questions
Why is Grit Real Estate selling its Kenyan properties?
Grit is pursuing a wider portfolio disposal and deleveraging programme amid financial pressure, higher financing costs and restructuring requirements. The proposed disposals form part of its broader corporate strategy.
How much are Grit's Kenyan properties worth?
The Kenyan income-producing portfolio was last reported at approximately US$158.2 million, equivalent to KSh20.5 billion, as at June 2025. This is a historical portfolio valuation, not a confirmed current sale price.
Which Kenyan properties are included?
Grit's published portfolio identifies Rosslyn Grove, Buffalo Mall, Eneo at Tatu City, Orbit Africa and Imperial Distribution Centre.
Have the properties already been sold?
The announced disposal process should not be confused with completed transfers. Grit has disclosed conditional transaction arrangements, creditor support and continuing disposal work. Completion remains subject to applicable conditions and approvals.
Can institutional investors acquire these assets?
Potential acquisitions would depend on the disposal structure, seller authority, lender approvals, transaction terms and access to an authorised sale process. Interested buyers should seek independent legal and financial advice.
Does financial distress guarantee a discounted purchase?
No. A distressed corporate seller does not automatically imply that the underlying property is undervalued. Buyers must establish market value, liabilities, rental performance and completion costs.
Methodology and Research Limitations
This research note was prepared on 5 November 2026 using publicly available corporate disclosures and published reporting.
The portfolio valuation cited in this report relates to June 2025. It should not be interpreted as a November 2026 independent valuation or confirmed disposal consideration.
Transaction information reflects announcements available at the date of publication. The terms of proposed transactions, creditor arrangements and completion conditions may change.
Murivest's investment framework represents internal analytical commentary. It does not constitute an independent valuation, transaction audit or investment recommendation.
Hypothetical financing calculations are illustrative and do not represent Grit's actual debt allocation to individual properties.
References and Further Reading
- Business Daily Africa (2026). 'Distressed developer to sell Sh20bn prime Kenya assets'. 4 November 2026. Read publication .
- Grit Real Estate Income Group (2026). 'Update on strategic transaction, further portfolio disposal process and continued lender support'. 26 October 2026. Corporate announcement .
- Grit Real Estate Income Group (2026). 'Our Property Portfolio'. Corporate portfolio disclosure. View portfolio .
- Construction Kenya (2026). 'US Embassy Estate, Buffalo Mall for Sale in Debt Crunch'. 5 November 2026. Read publication .
- Business Daily Africa (2026). 'Grit's Sh20.9bn Kenya property empire under pressure'. Read publication .
Related Reading
Market Intelligence
Distressed Real Estate in Kenya: The Nakumatt Auction and the Anatomy of Secured Lending Recovery
22 min read
Market Intelligence
The Chiromo Disposition: Standard Chartered's Exit from Physical Banking and What It Signals for Westlands Commercial Property
18 min read
Market Intelligence
London Commercial Real Estate: Q2 2026 Market Intelligence for Institutional Investors
16 min read
Murivest Community
Investor Discussion
Discuss investment opportunities, market trends, lease activity, financing, and underwriting with the Murivest community.
Join the Discussion
Share investment insights, market commentary, or leasing observations.
Professional discussion only. All comments are moderated.
Loading…
No discussion yet — be the first to contribute an insight.
Ask Murivest Research
Submit a Research Question
Questions on underwriting, leasing, market fundamentals, or capital structures are answered by the Murivest desk.
Murivest Research